The storm is over, the rain has slowed down, and the ceiling still looks dry.
That is usually the moment homeowners assume the roof made it through without damage.
Unfortunately, storm damage does not always announce itself with water pouring through the ceiling. A lifted shingle may settle back down after the wind stops. Hail may bruise the material beneath the granules without leaving an obvious hole. Flashing can move just enough to let water enter during the next rain, not the storm that caused the damage.
By the time a ceiling stain appears, moisture may have already reached the roof decking, insulation, framing, or drywall.
That does not mean every storm requires a new roof. It does mean homeowners should know what to check, what not to touch, and when to call a professional.
This guide explains what to do after severe weather, how to document possible roof damage, when emergency roof repair is necessary, and how to avoid making an insurance claim more difficult than it needs to be.

What Should You Do After a Severe Storm Damages Your Roof?
After a severe storm, stay off the roof, check the attic and ceilings for water, photograph visible damage, prevent additional water intrusion, contact your insurance company, and schedule a professional roof inspection. Avoid permanent repairs until the damage has been documented and the insurance process is clear.
Start Inside the House, Not on the Roof
Many homeowners immediately walk outside and look up at the shingles. That can be useful, but the first inspection should begin indoors.
Check the rooms beneath the roof, especially around chimneys, skylights, bathrooms, attic access points, and exterior walls.
Look for:
- Fresh ceiling stains
- Damp drywall
- Water around light fixtures
- Peeling paint
- Wet attic insulation
- Dark areas on the roof decking
- Musty odors
- Dripping near vents or chimneys
- Bulging sections of ceiling
A roof leak after a storm does not always appear directly below the damaged area. Water can travel along a rafter, roof deck, pipe, or layer of insulation before reaching the ceiling.
That is why patching the spot directly above a water stain often fails. The stain shows where the water finished its path, not necessarily where it entered.
Do not touch wet electrical fixtures. If water is near wiring, outlets, or ceiling lights, avoid the area and contact a qualified professional.
Do Not Climb onto a Storm-Damaged Roof
Even homeowners who are comfortable using ladders should stay off the roof after severe weather.
Wet shingles are slippery. Loose roofing material may move underfoot. Tree impact can weaken the decking without creating an obvious opening. A section that looks solid from the ladder may not support a person’s weight.
You can still perform a useful ground-level inspection.
Walk around the home and look for:
- Missing shingles
- Shingles folded over or out of position
- Pieces of roofing material in the yard
- Bent gutters
- Dented downspouts
- Damaged roof vents
- Loose flashing
- Fallen tree limbs
- Sagging roof sections
- Exposed roof decking
- Damage around the chimney
- Shingle granules near downspout exits
Use binoculars or the zoom function on your phone instead of climbing. Take pictures from several angles.
One important detail: a shingle in the yard does not automatically mean it came from your house. After strong winds, debris can travel from nearby properties. Photograph it, but also compare its color and condition with the shingles on your roof.
Wind Damage Is Often Less Obvious Than Missing Shingles
Most people picture wind damage as an empty section of roof where shingles have blown away.
That is only one type of damage.
Wind can lift the edge of a shingle, break the adhesive seal, and then allow the shingle to fall back into place. From the ground, the roof may look normal. During the next storm, the unsealed shingle can lift again and allow wind-driven rain underneath it.

Common signs of wind damage include:
- Creased shingles
- Lifted edges
- Broken adhesive seals
- Missing ridge-cap shingles
- Exposed underlayment
- Loose metal flashing
- Bent drip edge
- Damage near roof corners and edges
Roof edges, ridges, and corners usually receive more wind pressure than protected areas in the middle of a roof. These locations deserve close attention during a storm damage roof inspection.
Hail Damage Does Not Always Look Like a Hole
Hail damage is easy to misunderstand because it can look different depending on the roof material, hail size, wind direction, roof age, and angle of impact.
On asphalt shingles, hail may cause:
- Round areas of granule loss
- Dark impact marks
- Exposed asphalt
- Cracks in the shingle surface
- Bruising beneath the surface
- Small fractures in the fiberglass mat
A hail bruise may feel soft when inspected by a trained roofer, but homeowners should not press on shingles or walk across the roof to look for damage.
Metal components can provide useful clues. Dents in gutters, downspouts, roof vents, flashing, or air-conditioning fins may indicate that hail reached the property.
However, a few dents do not prove the entire roof needs replacement. A qualified inspection should evaluate the pattern, location, and severity of the impacts rather than treating every mark as major roof damage.
Fallen Trees Require More Than a Shingle Repair
When a branch hits a roof, the visible damage may only be part of the problem.
A large limb can crack decking, shift rafters, loosen flashing, damage gutters, or change the roofline. Removing the branch does not automatically make the structure safe.

Leave the home or affected area if you notice:
- A sagging roofline
- Cracked rafters
- Broken trusses
- A ceiling that has moved
- New cracks in interior walls
- Popping or shifting sounds
- A large opening in the roof
- A tree resting on the structure
Do not cut or pull a heavy branch from the roof yourself. The branch may be supporting damaged materials, and moving it can cause additional collapse.
Tree removal, structural stabilization, and emergency roof repair should be coordinated by qualified professionals.
Photograph More Than the Roof
Good storm damage documentation tells the full story.
Do not take one picture of a missing shingle and assume it is enough. Photograph the condition of the entire property before cleanup or temporary repairs begin.
Useful photographs include:
- Wide views of every side of the home
- Close views of visible roof damage
- Fallen branches before removal
- Damaged gutters and downspouts
- Dented vents or flashing
- Water stains inside the home
- Wet insulation
- Damaged furniture or flooring
- Debris in the yard
- Temporary tarps
- Receipts for emergency work
Write down when the storm occurred and when you first noticed the damage.
Keep estimates, invoices, emails, photographs, claim documents, and receipts in one folder. This makes it easier to respond when an adjuster or contractor asks for information later.
A weather report may confirm that a storm moved through the area, but it does not show what happened to your particular roof. Property-specific photographs and a written roof inspection are far more useful.
Should You Tarp the Roof Before the Adjuster Arrives?
Homeowners are generally expected to take reasonable steps to prevent additional damage after a covered loss.
That may include emergency roof tarping, removing standing water, moving belongings away from a leak, or placing containers beneath dripping water.
A tarp may be needed when:
- Shingles are missing
- Decking is exposed
- A branch created an opening
- Water is entering the attic
- Flashing was pulled loose
- A roof vent was damaged
Document the damage before the tarp is installed whenever it is safe to do so.
Do not install the tarp yourself. A poorly secured tarp can blow away, create new holes, trap moisture, or send a homeowner onto an unsafe roof.
Temporary roof repair should stop further water entry without covering up the original damage more than necessary.
It is also important to understand that a tarp is not a finished repair. It is a short-term measure used until the roof can be properly evaluated and restored.
Contact the Insurance Company, but Read the Policy Too
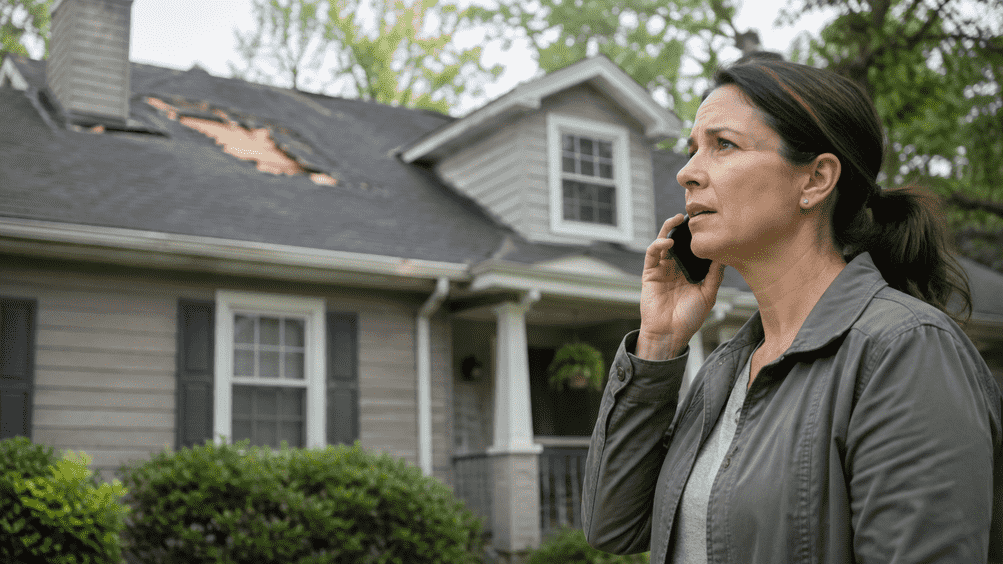
After documenting the damage, notify your insurance company or agent.
Ask specific questions instead of simply saying, “My roof was damaged.”
Find out:
- What deductible applies
- Whether there is a separate wind or hail deductible
- Whether the roof is covered at replacement cost or actual cash value
- Whether an adjuster will inspect the property
- What temporary repairs are allowed
- What receipts should be saved
- Whether permanent work should wait until after inspection
- What deadlines apply to the claim
Coverage depends on the policy, the cause of damage, the age and condition of the roof, exclusions, endorsements, and previous repairs.
A roofing contractor can document storm damage and provide an estimate. The contractor does not decide whether the claim is covered. That decision belongs to the insurance company.
Actual Cash Value and Replacement Cost Value
These terms create confusion during many roof insurance claims.
- Actual cash value generally accounts for depreciation. The insurer may estimate the replacement cost and subtract an amount based on the roof’s age and condition.
- Replacement cost value generally refers to the cost of replacing covered materials with similar materials, subject to the policy terms.
Some claims are paid in stages. The homeowner may receive an initial payment based on actual cash value, then receive recoverable depreciation after the work is completed and the final invoice is submitted.
Do not assume all roof policies work the same way. Older roofs may have different settlement terms, deductibles, or coverage limitations.
Do Not Approve Permanent Repairs Too Quickly
Stopping active water intrusion is urgent. Choosing the final repair method should be more deliberate.
A rushed patch can make it harder to identify the original damage. It can also create a repair that does not match the surrounding roof, does not address hidden moisture, or does not meet manufacturer requirements.
Before approving permanent storm damage roof repair, make sure the contractor has evaluated:
- The full roof surface
- Roof age
- Shingle condition
- Underlayment
- Flashing
- Roof decking
- Attic moisture
- Ventilation
- Valleys
- Penetrations
- Gutters and drainage
- Previous repairs
The correct scope may be a small repair, replacement of one roof slope, or complete roof replacement. The answer should come from the condition of the roof, not from the size of the insurance check.
A storm-damaged roof does not automatically need to be replaced.
A targeted repair may make sense when:
- The damage is limited to one area
- The surrounding shingles remain in good condition
- The roof is not near the end of its expected service life
- The decking is dry and structurally sound
- Compatible replacement materials are available
- The roof has not developed repeated leaks
Replacement may be the more practical option when:
- Damage appears on several slopes
- Large areas contain creased or missing shingles
- Water reached the decking or insulation
- The roof was already showing significant wear
- Repairs have been made repeatedly
- Suitable replacement shingles cannot be matched
- The roof has installation problems beyond the storm damage
- The repair cost is high compared with the remaining roof life
There is no single percentage of damage that determines the answer in every situation.
Two roofs with the same number of missing shingles may need different solutions. A five-year-old roof with localized damage is not the same as a twenty-year-old roof with brittle shingles, poor ventilation, and previous leaks.
This is where an honest inspection matters.
What a Real Roof Inspection Should Include
A storm damage inspection should involve more than circling a few spots with chalk.
The contractor should examine:
- Shingle seals and fasteners
- Ridge and hip shingles
- Valleys
- Chimney flashing
- Skylights
- Pipe boots
- Roof vents
- Wall-to-roof transitions
- Drip edge
- Gutters and downspouts
- Soffit and fascia
- Roof decking
- Attic insulation
- Moisture patterns
- Ventilation
- Structural movement
The contractor should also explain whether the issue appears storm-related, age-related, installation-related, or caused by maintenance problems.
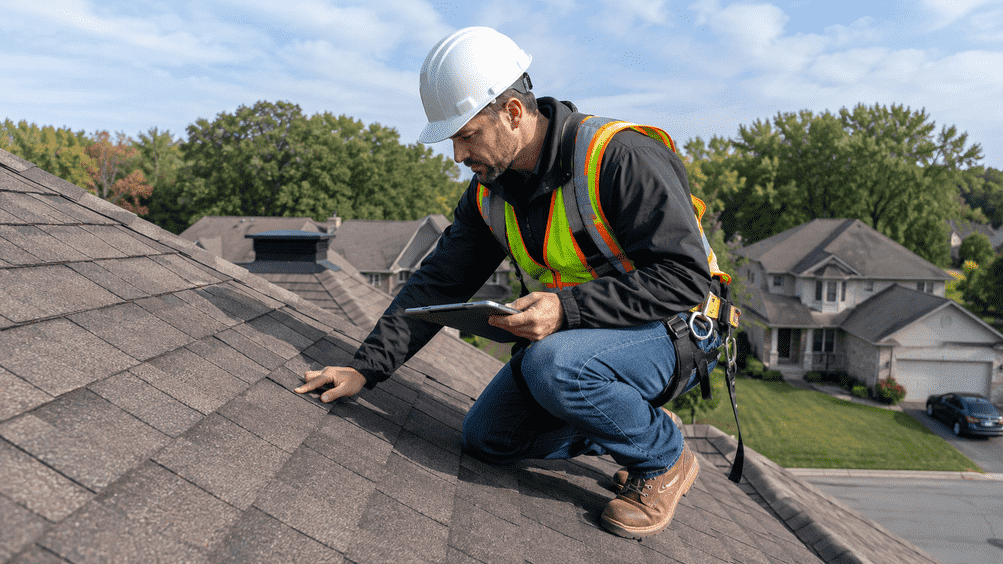
Ask for dated photographs and a written estimate. A useful estimate should identify the materials, quantities, labor, flashing details, cleanup, decking allowances, and warranty information.
A vague one-page proposal with a large total and no scope is not enough for a major roofing project.
Be Careful with Contractors Who Arrive Immediately After the Storm
After a large storm, homeowners often receive calls, flyers, and door knocks from companies they have never heard of.
Some are legitimate roofers. Others are temporary storm-chasing crews that leave the area once the work slows down.
Be cautious when a contractor:
- Pressures you to sign during the first visit
- Guarantees insurance approval
- Offers to “handle everything” without explaining the process
- Demands full payment upfront
- Cannot provide proof of insurance
- Uses a temporary address
- Refuses to provide a detailed contract
- Asks you to sign a blank form
- Tells you not to speak with your insurer
- Will not explain the repair scope
A professional roofing contractor should be willing to explain what was found, show photographs, discuss repair and replacement options, and give you time to review the proposal.
Urgency is appropriate when water is entering the home. Pressure is not.
How Homeowners Can Reduce Future Storm Damage
No roof is storm-proof, but routine maintenance can reduce preventable damage.
Before storm season:
- Replace loose or damaged shingles
- Repair deteriorated flashing
- Clear gutters and downspouts
- Trim dead or overhanging branches
- Check attic ventilation
- Inspect sealant around penetrations
- Secure loose exterior items
- Keep roof documents and warranties accessible
- Review insurance deductibles
- Photograph the exterior of the home
If replacement is already being planned, ask the contractor about wind-rated shingles, impact-resistant materials, improved roof deck attachment, sealed roof decking, and upgraded flashing details.
The best time to prepare for a roof claim is before one happens.
Schedule a Storm Damage Roof Inspection with CPS Construction Services
After a severe storm, homeowners need clear answers, not a sales pitch.
CPS Construction Services evaluates missing shingles, hail impacts, damaged flashing, roof leaks, fallen-tree damage, and other storm-related roofing problems. We document what we find, explain whether repair or replacement makes sense, and help homeowners understand the work their roof actually needs.
Contact CPS Construction Services to schedule a professional storm damage roof inspection before the next rainfall turns a manageable repair into a larger problem.
Frequently Asked Questions
Make sure the home and surrounding area are safe. Stay off the roof, check ceilings and the attic for water, photograph visible damage, move belongings away from leaks, and contact your insurance company. Schedule a professional roof inspection as soon as possible.
Look for missing shingles, lifted edges, creased tabs, loose ridge caps, exposed underlayment, bent flashing, and roofing debris in the yard. Wind can break the seal beneath a shingle without removing it, so damage may not be visible from the ground.
Hail damage may appear as dark impact marks, missing granules, exposed asphalt, cracks, or bruising beneath the shingle surface. Dents in gutters, roof vents, flashing, or downspouts can also indicate hail exposure.
You can contact both within the same general timeframe. Notify the insurer promptly, then schedule a roofer to inspect and document the damage. The insurer determines coverage, while the roofer evaluates the roof and prepares the repair scope.
Yes, temporary protection may be necessary to prevent additional damage. Photograph the original condition first when safe, use a qualified professional to install the tarp, and save all receipts. Avoid unnecessary permanent repairs before the adjuster documents the loss.
Verify the contractor’s local business information, insurance, references, written warranty, payment schedule, and detailed scope. Avoid anyone demanding full payment upfront, guaranteeing insurance coverage, or pressuring you to sign before you understand the work.


